Aya Gold & Silver says an updated preliminary economic assessment puts Boumadine's after-tax NPV at C$3.5 billion, while Zgounder is generating cash flow. The figures are projections and company-reported operating claims, not a completed feasibility study or independent verification of project delivery.
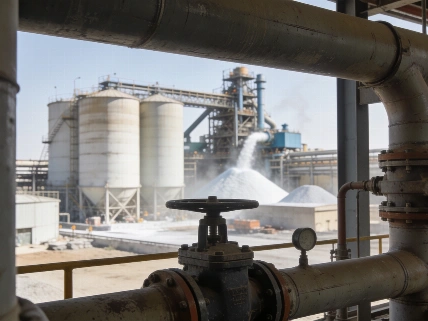
Zgounder is reported to have ramped up production above its designed capacity, according to a summary of Aya Gold & Silver's presentation at Mining Forum Americas 2026. The same summary puts Boumadine's after-tax net present value at C$3.5 billion, up from C$1.7 billion in the earlier preliminary economic assessment. The updated estimate reflects resource updates.
The new Boumadine estimate also gives an internal rate of return of 93%. That figure assumes gold at US$3,500 per ounce and silver at US$50 per ounce. Projected average annual cash flow is about C$1.1 billion over a 14-year mine life. These are model outputs, not operating results. They depend on the stated assumptions. Some secondary accounts have reported the NPV figures in US dollars; the assessment figures cited here are in Canadian dollars.
Zgounder is the operating counterpart to Boumadine's projected value. Aya is reported to be generating about C$170 million in annual net cash flow after expenses. Later reports put the company's cash balance at about US$182.8 million at the end of the second quarter of 2026. Those reports also give revenue of US$96.8 million and Zgounder production of 1.5 million ounces of silver. This could help fund development. It does not establish how much capital Boumadine will need or how Aya will finance it.
The distinction matters. Zgounder's cash flow is an operating measure. Boumadine's NPV and projected returns depend on estimates, prices and future execution. Independent commentary has described Zgounder's cash generation as a possible funding bridge for Boumadine. That is not confirmation that the cash will cover all future development costs.
The presentation summary said construction had started ahead of a feasibility study. Other reports said infrastructure work was expected to begin in the fourth quarter of 2024, with a feasibility study anticipated in the second half of 2027. The reported construction activity is not defined. It should not be read as proof that full mine construction is under way or that a final feasibility study is complete.
The presentation described Morocco as a stable, mining-friendly environment with rapid permitting and strong infrastructure. These are Aya's assessments, not independent confirmation of Boumadine's permits, schedule or economics. An earlier Morocco assessment discusses the country's broader industrial and infrastructure profile for investors. It does not verify Aya's project claims.
For regional context, MAP reporting and analysis by the UN Economic Commission for Africa (UNECA) can inform discussion of national and regional economic conditions. Neither is cited here as validation of Aya's project estimates or permitting status. Keep that broader context separate from the company's claims about resources, valuation and execution.
The account draws on an AI-generated summary of the September 29, 2026 audio transcript. It carries a warning that it may contain inaccuracies. Its central points are Aya's reported cash generation at Zgounder and the higher projected NPV at Boumadine. The gap remains important. Zgounder is an operating mine; Boumadine is still awaiting a feasibility study.